Digital finance 2030: Data, AI, and three priorities through a technology lens
Digital transformation is opening up significant room for the finance sector to operate more effectively and serve citizens and businesses better. According to technology expert Duong Tat Toan, three challenges deserve priority on the road to 2030: data integration, legacy system modernization, and governed AI adoption. Proactive taxation offers a glimpse of the value unlocked when all three are addressed.
Plenty of headroom, but data is the starting point
In a recent conversation with Tạp chí Kinh tế – Tài chính (Economic and Finance Review), I was asked what the most pressing challenge in the finance sector’s digital transformation is. My answer: data. This article goes deeper into that answer.
The finance sector is already ahead on many fronts. From the start of 2026 through March 13 alone, the system received and processed around 2.4 billion e-invoices, and a cumulative 463,855 businesses now issue invoices generated directly from cash registers (Tạp chí Kinh tế – Tài chính). Since January 1, 2026, household businesses have moved from presumptive (lump-sum) taxation to self-declaration (VOH). Every one of these figures adds another stream of data flowing into the sector.
But more data doesn’t mean usable data. Data only creates value when it is complete, accurate, consistent, and available in real time, and every AI application or digital service is built on that foundation. Many sources still need to be integrated into a single, unified system. That is why Resolution 57-NQ/TW, implemented through Government Resolution 214/NQ-CP, makes building and completing databases a core mission. From a technology standpoint, I see three challenges worth prioritizing, and they build on one another.
Challenge 1: From data silos to a national financial database
An importer today deals with tax, customs, and social insurance authorities at the same time, and each holds a different piece of information about the same company.
That is the broader picture of data in the finance sector: rich, but fragmented. Even after restructuring and consolidation, each unit still runs its own systems and databases. Yet every bigger ambition, from public services that never ask you to re-enter information to AI-assisted decision-making, depends on data that is complete, accurate, and consistent.
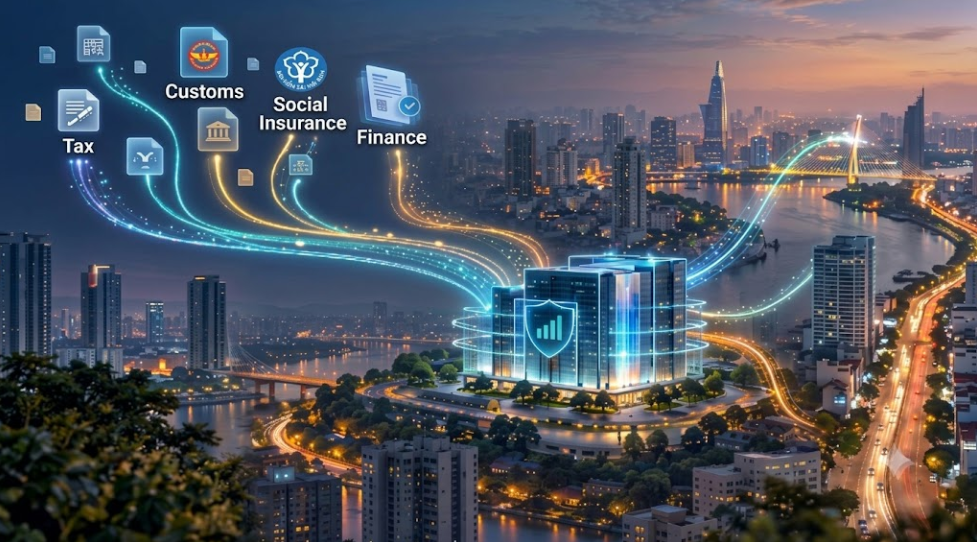
The immediate task is to integrate tax, customs, State Treasury, insurance, and related data into a national financial database. Getting there requires an enterprise-wide data architecture framework, with a clear integration roadmap and governance policies that ensure data is used effectively and lawfully.
Once that foundation is in place, financial data can become a resource for the entire digital economy. One example: with their consent, citizens could get loans approved faster because banks can rely on always-up-to-date tax information.
Challenge 2: Legacy system modernization, not rip-and-replace
Almost every organization runs systems built years ago, at different times, to different standards and levels of quality. They still power day-to-day operations and hold most of the historical data.
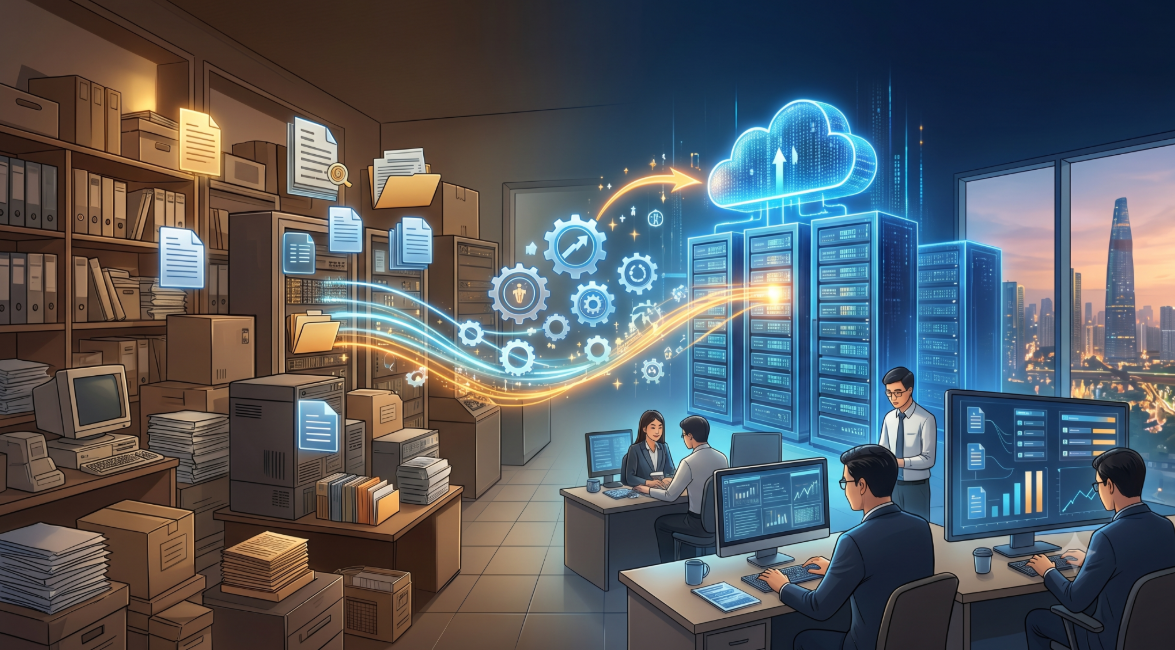
That’s why transformation can’t simply be a “rip-and-replace” of old systems with a new platform. Alongside building centralized platforms and databases, organizations need to manage their entire existing data estate. I recommend four steps:
1. Profile the data and assess its quality in each source system, then decide on the right approach to governance and migration.
2. Analyze the design models of legacy data systems to build safe, complete migration solutions. This takes experienced specialists.
3. Standardize and enrich data with supplementary sources and build a data dictionary, so legacy data keeps creating value on the new platform and becomes high-quality fuel for AI.
4. Apply common data standards and share data accordingly across government agencies, which is increasingly a mandatory requirement, and publish open datasets that encourage businesses and organizations to innovate and deliver valuable data services to the digital economy.
Do all four, and the new system inherits the value of what exists today while staying flexible enough for AI and whatever comes next. Cut corners, and bad data from legacy systems flows straight into the new platform.
Challenge 3: Governed AI adoption, from low-risk tasks to core functions
In a sector that handles data as sensitive as finance does, how you introduce AI matters as much as the technology itself. I group operations by risk level:
| Function group | Examples | How to introduce AI |
| Low risk | Q&A, procedural guidance, information lookup | Pilot early, scale fast |
| Core | Risk assessment, case classification, decision support | Deploy within a controlled scope; evaluate before scaling |
This approach lets the sector capture value early while buying time to build controls for high-stakes decisions.
To go further, the sector needs centralized AI infrastructure that integrates its data with other ministries and the National Data Center. That infrastructure includes a high-performance big data platform, a sovereign AI platform, and cloud-based data centers.
People remain at the center. AI-assisted decisions must be transparent and contestable, and experts step in whenever results look anomalous.
Proactive taxation: what happens when the three challenges are solved
Picture a household business owner who has just completed a sale, and the tax obligation for that transaction has already been determined inside the point-of-sale software, without waiting for the filing period. That is what I call “embedded tax,” or more broadly, proactive taxation. Taxpayers no longer have to figure out, calculate, and file on their own. Connecting e-invoice data to the tax authority is a step in exactly this direction.
This step already has a legal basis. Under the amended Law on Tax Administration, from January 1, 2026, household businesses that use e-invoices coded by the tax authority will have their VAT and personal income tax liabilities determined by the system and updated for them on eTax and the National Public Service Portal (VOH). The business owner above is no longer a distant hypothetical.
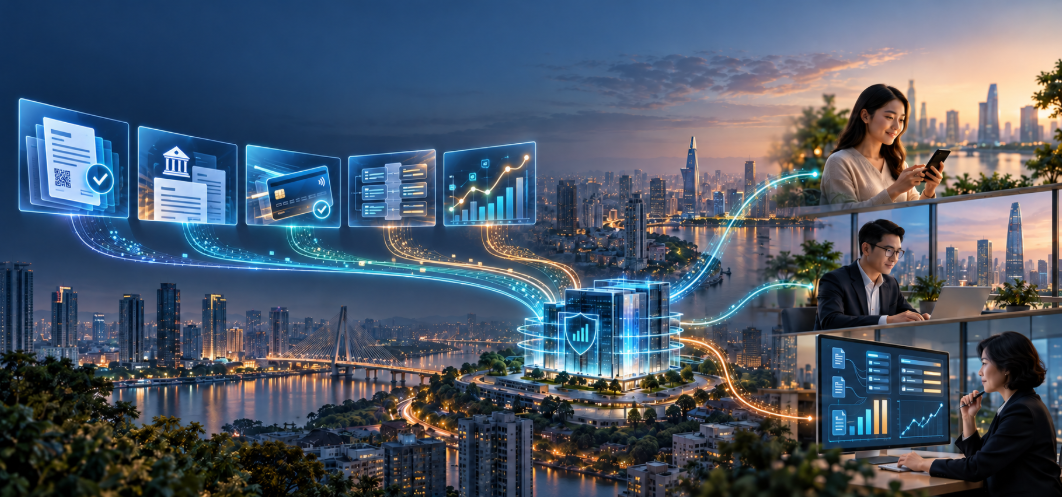
The reference framework is the OECD’s Tax Administration 3.0 report (September 2023): moving tax processes into the very systems taxpayers already use to run their businesses, transact, and communicate. Many tax administrations have used this framework to guide their digital transformation strategies (OECD, 2023).
Each group of taxpayers has its own “natural system,” so the point where tax gets embedded differs:
| Taxpayer group | Where tax is embedded | Today | With proactive taxation |
| Individuals | VNeID (national digital ID), payroll platforms, digital platforms | Must work out obligations themselves; late settlement when buying property or working across borders | Automatic withholding on payday; tax impact simulated before a transaction; one-time declaration for life events |
| Household businesses and SMEs | Cash registers, accounting software, e-commerce marketplaces | Complex rules; every change in business model adds a new burden | Tax calculated within the transaction; AI-assisted registration and conversion to a company; tax status always available |
| Multinational groups | ERP, digital logistics chains | A different standard in every country; audits years after the transaction | Rules updated before transactions close; reporting to international standards; group-wide tax risk always current |
What all three share: tax is embedded, built on trusted digital identity, near real time, combining AI with human expertise, and powered by standardized, interoperable data. The tax authority’s role shifts from processing individual transactions to overseeing systems so that automation runs correctly. All five elements trace back to the three challenges above. Without unified data, proactive taxation will remain a collection of isolated pilots.
Defining success metrics for 2030
Every journey needs a yardstick. In my view, a smart, secure, connected, and sustainable digital finance ecosystem shouldn’t be measured by the number of systems built, but by the changes that citizens, businesses, and public officials actually feel.
| Stakeholder | Burden today | Signs of success in 2030 |
| Citizens | Only learn about their obligations when a situation arises | See and access their own data; track tax obligations continuously; receive important updates in real time |
| Businesses | Heavy tax, insurance, and customs procedures | Significantly fewer procedures; business systems deeply integrated with the finance sector |
| Regulators | Fragmented ecosystem; officials handle much of the work manually | Data and AI automate operations and support recommendations, policymaking, and executive decision-making |
As data becomes connected and integrated, many of the obligations citizens and businesses have to the State will be fulfilled more automatically.
Closing thoughts
As I envision it, by 2030 a citizen will open VNeID and immediately see their tax obligations. A household business owner will finish a sale with the tax already calculated correctly. And finance sector officials will spend their time on analysis and policy rather than paperwork.
The technology for that picture is ready. What will make the difference is a unified data architecture, lawful data governance, and a step-by-step, controlled approach to AI. These are the areas where technologists like us stand ready to work alongside the finance sector, from architecture consulting and data standardization to AI platforms.
Sources
- Data and AI will shape the digital finance ecosystem by 2030 — Journal of Economics and Finance, October 2, 2026
- OECD – Tax Administration 2023
- Journal of Economics & Finance – 2.4 billion electronic invoices
- VOH – Abolishing flat tax
| Exclusive article by an FPT IS expert, FPT Corporation.
Duong Tat Toan, Chief Technology Officer of Government Sector, FPT IS, FPT Corporation |